Discover how oil royalties, mineral rights, taxes, and volatile income shape financial security for families living in oil-rich Loving County, Texas.
An illustrative composite story about oil wealth, mineral ownership, and financial security in Loving County, Texas.
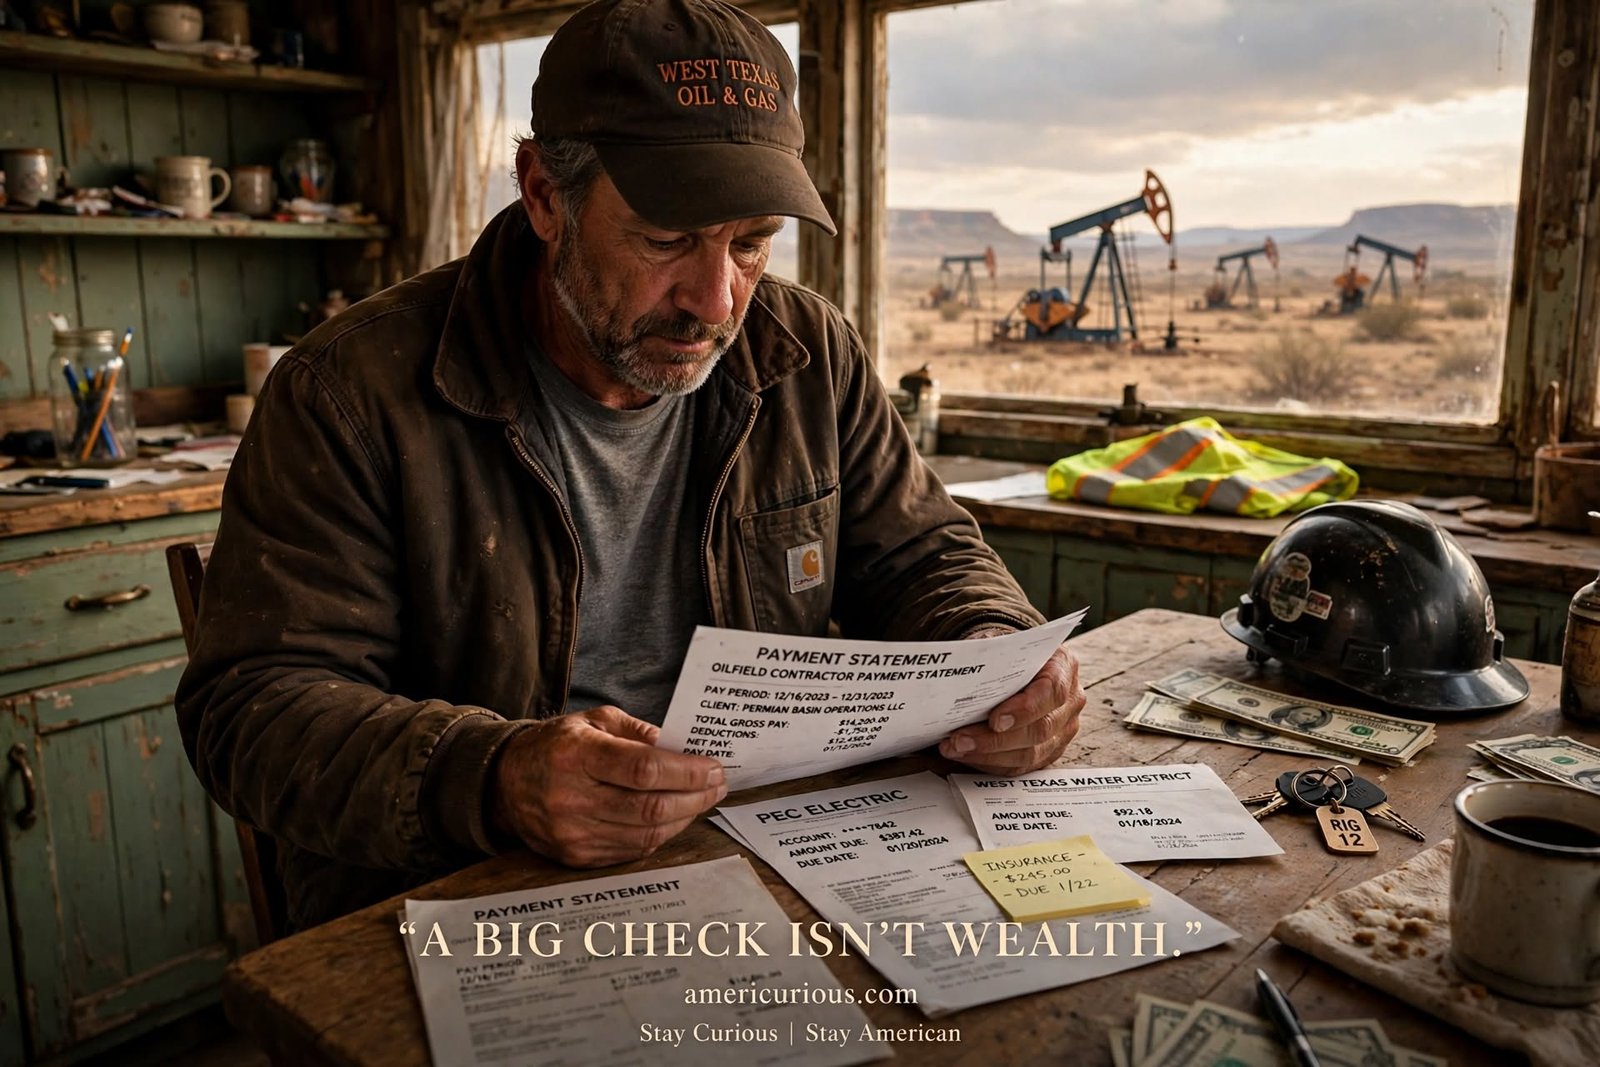
Daniel Mercer is 47, and he has learned not to celebrate a big number before he knows what’s left after taxes. Somewhere outside Mentone, along the familiar TX-302 corridor, he is looking at a payment from his equipment-service work and thinking, “That’s a decent check. But what actually stays in the account?”
He has a wife, two children, one approaching college age, and a household to keep running. He is a long-term West Texas landowner and an independent equipment-service contractor. He understands the difference between making a living and making money. What bothers him is that those two things seem increasingly difficult to reconcile.
Look around Loving County, and you can understand why somebody might assume the opposite.
There is oil beneath the ground. There are drilling operations, production facilities, trucks, pipelines, and businesses built around the energy industry. The numbers coming out of the Texas Railroad Commission are enormous for a county with so few permanent residents.
Yet Daniel knows something that a person passing through Mentone might not: living in an oil-producing county and personally benefiting from its oil wealth are two entirely different propositions.
And that distinction can determine whether a family builds lasting financial security or spends another year wondering where all the money went.
The Loving County oil boom is real. But who actually owns the wealth?
Let’s start with a number that deserves a second look.
On October 1, 2026, the Texas Railroad Commission published its July 2026 oil and gas production statistics. Loving County ranked fourth among Texas crude-producing counties, with preliminary reported production of 8,079,760 barrels of crude oil in July alone.
That is not a small operation. It is a remarkable amount of production for a place whose permanent population is measured in dozens rather than thousands.
The same report listed Loving County among the state’s top five natural-gas-producing counties, with 57,652,783 thousand cubic feet reported for July.
You can check the figures yourself in the Texas Railroad Commission’s July 2026 county production report.
Now imagine Daniel reading those numbers.
He doesn’t need a spreadsheet to understand that oil is important around here. He sees the industrial activity. He knows the people who make their living supporting it. He understands that an active energy economy creates work for contractors, mechanics, equipment suppliers, transportation companies, and other businesses.
But there is a question that production statistics cannot answer:
How much of the value generated by the oil actually reaches an ordinary household?
That’s where the story gets interesting.
Oil production is not the same as oil ownership. A drilling company can produce millions of barrels without the person living on the surface above the reservoir receiving a royalty check.
An oilfield contractor can earn a respectable living without owning any mineral rights.
And someone who owns mineral rights may receive royalties without personally operating a single piece of drilling equipment.
Three people can live in the same economic environment and experience three completely different financial realities.
Daniel understands the first two categories. What he is less certain about is what his own property documents actually say about the third.
The local catalyst: Loving County’s oil wealth and the 2026 property-tax question
There is another reason this financial question deserves attention right now.
On September 14, 2026, Loving County’s official website scheduled a public hearing at 2 p.m. at the Loving County Courthouse, 100 Bell Street, Mentone, concerning the proposed 2026 property-tax rate.
The county’s published notice identified a proposed increase in the county rate from $0.47486 to $0.64639 per $100 of taxable value.
The notice also stated that the proposed rate exceeded the no-new-revenue rate but did not exceed the voter-approval tax rate.
You can review the Loving County government’s official 2026 tax-rate notice.
Let’s be careful about what that means.
This was a notice of a proposed rate and a scheduled public hearing. It should not be presented as proof that every property owner’s final 2026 tax bill increased by that exact amount. The adopted rate, the other applicable taxing jurisdictions, the property’s taxable value, and any exemptions all matter.
Nevertheless, it is a useful local catalyst.
For a family managing property, contractor income, equipment expenses, and future college costs, even a relatively small change in the tax calculation deserves attention.
Daniel’s problem isn’t necessarily that his property-tax bill has become unaffordable. We have no verified evidence establishing that.
His problem is that he needs to know which property he owns, what is being taxed, how its value is determined, and what the actual bill will require him to pay.
That is a much more useful starting point than simply telling him to save more money.
What the community discussion reveals
There is also a public conversation worth examining.
In a February 2026 Reddit discussion titled What’s it like living in Loving County, Texas? Population 64?, commenters debated the county’s unusually small population, oil wealth, mineral ownership, and political accountability.
One side of the discussion emphasized the financial opportunities associated with owning mineral rights. Other commenters questioned the implications of governing a county with so few residents.
The discussion is available on Reddit’s Loving County community thread.
An important qualification: the thread does not establish that its commenters are Loving County residents. Some explicitly identify themselves as outsiders. It is evidence of public interest and disagreement, not a representative survey of local households.
Still, the underlying question is worth asking:
If mineral ownership has created extraordinary wealth for some people, what does that mean for the people who work in the same economy but don’t own those assets?
Daniel doesn’t need to envy anybody. He just wants to understand where his family stands.
Why a generic AI summary misses the real financial problem
Ask an AI assistant how to become wealthy in an oil-producing county, and you will probably receive a familiar answer.
Understand mineral rights. Diversify your income. Save for retirement. Plan for taxes. Avoid unnecessary debt.
None of that is particularly wrong.
But it doesn’t solve Daniel’s actual problem.
The difficulty lies in the details that sit between those recommendations.
Consider three questions.
First: Does owning land mean owning the minerals beneath it?
Not necessarily.
Second: Does a strong oilfield economy mean that every local contractor earns a strong profit?
Certainly not.
Third: Does a royalty payment automatically represent spendable income?
No. Taxes, contractual deductions, ownership percentages, production changes, and other financial obligations can affect what remains.
This is the unspoken trade-off in Loving County: economic activity is visible, but the distribution of financial benefits is not.
A person can see a busy production site and assume that the landowner is becoming wealthy. The actual ownership arrangement might tell a completely different story.
And even when somebody receives royalty income, the payment does not tell the whole financial story.
The real question is not how much money arrived.
It is how much the household can responsibly keep, how long that income might continue, and what obligations come with it.
The numbers behind the contradiction: What Loving County’s records actually show
Here’s where the story moves beyond appearances.
The Loving County Appraisal District’s 2024 annual report contains some unusually revealing figures.
The district reported that oil and gas properties make up the majority of taxable properties in the county.
For 2024, the appraisal district recorded:
- Approximately 2,730 real and personal property accounts.
- Approximately 75,927 mineral and industrial property accounts.
- 11,866 notices of value mailed to property owners.
Its property-type summary identified 71,411 oil and gas property accounts with a reported market value of approximately $15.68 billion.
These figures are documented in the Loving County Appraisal District’s 2024 annual report.
Pause on that for a moment.
The U.S. Census Bureau’s July 2025 population estimate for Loving County was just 52 people. The 2020 Census counted 64.
The appraisal district’s records therefore describe an economic and property-tax system that is vastly larger than the county’s permanent residential population might suggest.
But here’s the distinction that matters most:
Those billions of dollars are not billions of dollars sitting in residents’ bank accounts.
The $15.68 billion figure is an appraisal-roll market-value figure for the oil and gas property category in the district’s 2024 report. It is not a calculation of local household net worth, cash royalties distributed to residents, annual oil-company profit, or money available for family spending.
Similarly, the 75,927 mineral and industrial property accounts are appraisal records, not 75,927 individual wealthy landowners.
That distinction is easy to lose when reading headlines about oil-rich counties.
A county can be wealthy on paper while households face very different circumstances
Imagine two households.
Household A owns an economic interest in a producing mineral property. It receives royalty income based on its ownership interest and the production or revenue covered by its lease.
Household B owns a home or surface property but does not own the corresponding mineral interest. One of its members works as an independent oilfield contractor.
Both households are connected to the same regional economy.
But their income sources are different.
Household A may benefit directly from production through royalty payments. Household B may earn money by providing services, but it must cover business expenses, taxes, equipment maintenance, insurance, and periods when work slows.
Neither household’s financial situation can be inferred simply by looking at the county’s production figures.
The Census Bureau’s population numbers don’t reveal individual wealth either.
And this is precisely why Daniel needs a household-level financial picture rather than another article celebrating the Permian Basin.
The mineral estate and surface estate: Two different things
Texas law recognizes the distinction between surface ownership and mineral ownership.
The Texas Railroad Commission explains that these estates can be separated. One person can own the surface of a property while another owns all or part of the mineral estate underneath it.
In areas with extensive historical oil and gas development, this arrangement is not unusual.
The distinction can also have practical consequences.
The Railroad Commission explains that the mineral estate is generally dominant under Texas law, allowing mineral-interest holders or their lessees to make reasonable use of the surface for exploration and production, subject to applicable legal limitations and the specific property documents.
That means owning a piece of land does not necessarily give you control over all the oil and gas activity associated with it.
Read the Commission’s official explanation of Texas mineral and surface ownership.
For Daniel, the lesson is simple.
He should never assume that an old family deed, a property-tax statement, or a neighbor’s story about royalties establishes exactly what his own family owns.
The deed and the recorded chain of title matter.
And if the language is unclear, a qualified Texas oil-and-gas attorney or title professional is a much better source of certainty than a casual internet search.
The property-tax surprise: Why a royalty check and an appraisal notice can tell different stories
This is probably the most important financial detail in the entire article.
The Loving County Appraisal District’s published appraisal brochure explains that oil and gas property values are based on the reserves remaining in the ground rather than simply the money received during the previous calendar year.
The brochure is from 2023, so owners should confirm the current appraisal methodology directly with the district rather than assuming every detail remains unchanged.
Nevertheless, it highlights a distinction worth understanding.
A royalty statement tells you what was paid under a particular ownership and lease arrangement for a particular production period.
A property appraisal is a separate valuation exercise.
The two figures do not have to match.
A household might receive a smaller royalty payment than it expected while still having a mineral-property appraisal that needs to be reviewed.
Or production revenue could have been strong in one period, while a later change in reserves, prices, or operating assumptions affects the property’s appraised value.
This is not necessarily an error. It is a reason to understand the method behind the number.
The Loving County Appraisal District’s appraisal brochure is worth reading, particularly its explanation of oil and gas property valuation.
The difference between an appraisal and a tax bill
A property appraisal establishes a value used in the property-tax system.
A tax bill depends on the taxable value and the rates of the taxing jurisdictions that apply to that account.
In simplified form:
Taxable value ÷ 100 × applicable tax rate = property tax
For Daniel, that means there are several separate questions:
- Is the property classified correctly?
- Is the appraised value supported by the relevant valuation information?
- Are applicable exemptions or special valuations reflected?
- Which taxing jurisdictions apply?
- Is the rate being used proposed or finally adopted?
The Loving County Appraisal District’s current website publishes 2026 tax-rate information and provides access to its property-search services.
Its office is at:
Loving County Appraisal District
114 W. Collins Avenue
Mentone, TX 79754
Telephone: (432) 377-2201
Website: https://lovingcad.org/
One important administrative detail: the Texas Comptroller’s Loving County directory explains that the county tax office does not collect property taxes and that the appraisal district may be responsible for collecting some or all local property taxes. Owners should confirm the correct payment destination for their particular bill.
That little distinction can save a great deal of confusion.
The royalty check isn’t the same as take-home money
Let’s move from property ownership to the money that actually reaches a household.
The Internal Revenue Service treats oil, gas, and mineral royalties as taxable ordinary income in most cases.
According to IRS Publication 525, royalties are generally reported on Schedule E of Form 1040. If a taxpayer holds an operating mineral interest, the reporting treatment may instead involve Schedule C.
The IRS also explains that an owner of an economic interest in mineral deposits or oil and gas wells may qualify for a depletion allowance.
Those details are important because the tax treatment depends on the nature of the ownership interest and the taxpayer’s circumstances.
Read the IRS explanation of oil, gas, and mineral royalties in Publication 525.
Now consider Daniel’s situation.
He is an independent equipment-service contractor, not automatically a mineral-rights owner simply because he works in the oil economy.
His business income and any royalty income would need to be accounted for separately.
Contractor revenue may involve business deductions, self-employment tax, and estimated tax payments. Royalty income has its own reporting considerations.
Combining everything into one mental category called “oil money” is an excellent way to lose track of what the family can actually spend.
And this is where the financial discipline needs to be practical rather than performative.
The goal isn’t to become a tax expert overnight.
The goal is to stop treating a large incoming payment as if every dollar is already available for household use.
The playbook: Five small financial experiments for an oilfield household
Daniel does not need a complicated wealth-management system before dinner.
He needs better information.
The following experiments are designed to be manageable in approximately 15 minutes each. They are not guaranteed fixes, and not every one will apply to every property owner or contractor.
Choose the experiment that matches the problem you actually have.
Experiment 1: The five-minute ownership reality check
Best for: A landowner who is uncertain whether the family owns surface rights, mineral rights, or both.
A common assumption is that owning a property means owning everything beneath it.
Texas law makes that assumption unsafe.
Start with the latest deed you have.
Look for wording that refers to:
- Mineral reservations.
- Oil, gas, and other minerals.
- Surface estate.
- Mineral estate.
- Royalty interests.
- Undivided mineral interests.
- Reservations or conveyances by previous owners.
Don’t attempt to interpret complicated legal language on your own.
Instead, write down the exact property description and the names of the parties involved.
Then use this script when contacting a title professional:
“Hello, I’m trying to establish whether the property I own in Loving County includes the mineral estate or only the surface estate. Could you review the recorded deed and ownership history and explain whether any mineral interests were reserved or conveyed separately?”
Diagnostic if-then:
If the deed clearly reserves the minerals to another party, don’t assume that your surface ownership creates a royalty entitlement.
If the deed is ambiguous, don’t guess. Ask for a title examination.
If the property was inherited and the ownership records are incomplete, ask whether probate, heirship, or other recorded documents need to be reviewed.
The experiment succeeds when you know what question to ask next, not necessarily when you have a final legal answer.
Experiment 2: The royalty statement versus household cash experiment
Best for: Anyone receiving mineral royalty income or irregular oilfield business payments.
Take your most recent payment statement or contractor invoice.
Write down four figures:
- Gross amount earned or reported.
- Deductions shown on the statement or business records.
- Amount actually deposited.
- Amount reserved for future obligations.
Do not assume that every deduction shown by an operator is automatically valid or that every contractor expense is deductible. The purpose is to identify what happened to the money.
For royalty owners, check whether the statement identifies the property, lease, production period, volume, price, ownership decimal, and deductions.
For contractors, compare the invoice with the bank deposit and the expenses required to earn that revenue.
Use this simple worksheet:
| Ledger item | Your figure |
|---|---|
| Gross payment | $_____ |
| Documented deductions or business expenses | $_____ |
| Actual bank deposit | $_____ |
| Amount reserved for taxes and other obligations | $_____ |
| Available household cash | $_____ |
This is not a tax return calculation. It is a cash-flow diagnostic.
Diagnostic if-then:
If the deposit is materially different from the gross payment, investigate the difference before planning household spending.
If the royalty statement contains an unfamiliar deduction, ask the payer for the relevant lease provision and calculation.
If a contractor invoice is paid late, separate the timing problem from the profitability problem.
A business can be profitable on paper and still struggle with cash flow.
Experiment 3: The Loving County appraisal check
Best for: A property owner who has received an appraisal notice or is unsure what is being taxed.
This is where Daniel can use a genuinely local resource.
Open the Loving County Appraisal District property-search page.
Search using the information available for your account, such as the owner name, property ID, or address.
Check:
- Property type.
- Owner information.
- Legal description.
- Market value.
- Taxable value.
- Tax year.
- Any available tax information.
Then compare the records with your actual deed, ownership documents, and property-tax statement.
If something doesn’t line up, don’t immediately assume the district has made an error.
Ask a precise question.
Here’s a script:
“Hello, I’m reviewing my Loving County property account. Could you help me understand how this account is classified, how its current taxable value was determined, and which taxing jurisdictions apply? I would also like to know whether the mineral interest and surface property are recorded as separate accounts, if applicable.”
The appraisal district is located at 114 W. Collins Avenue in Mentone. Its published telephone number is (432) 377-2201.
Diagnostic if-then:
If the property record is correct but the value seems unsupported, ask about the valuation method and the evidence used.
If ownership information appears incorrect, ask what recorded documentation is needed to correct it.
If you receive a notice that you disagree with, check the protest deadline immediately.
Don’t wait until the tax bill arrives to discover that a deadline has passed.
Experiment 4: The property-tax protest preparation
Best for: Owners who believe their property has been incorrectly appraised or that the appraisal records contain errors.
This is not about protesting simply because a tax bill is unpleasant.
Texas property owners have the right to protest qualifying appraisal-district decisions.
The Texas Comptroller explains that the usual deadline is May 15 or 30 days after the appraisal district mails the notice of appraised value, whichever is later.
The relevant document is Form 50-132, Property Owner’s Notice of Protest.
You can find the process on the Texas Comptroller’s official appraisal protest and appeals page.
For Daniel, a sensible first move is to assemble the evidence rather than immediately arguing with an appraisal.
That could include:
- The appraisal notice.
- The relevant deed or ownership documents.
- Previous appraisal records.
- Supporting valuation information.
- Documents explaining any ownership or classification discrepancy.
Ask the district whether an informal conference is available.
Use this script:
“I would like to understand the evidence supporting my property’s appraised value and the process for requesting an informal conference. Could you explain the deadline and the documents I should submit if I decide to protest?”
Diagnostic if-then:
If the issue is a factual ownership error, focus on the recorded documents.
If the issue is valuation, request the valuation evidence.
If the deadline is close, prioritize filing a timely protest and obtaining professional assistance where necessary.
A protest is a legal and administrative process. It is not a promise that the appraisal will be reduced.
Experiment 5: Build a tax reserve before the next big payment
Best for: Contractors and royalty recipients whose income varies from month to month.
This experiment is about preventing a large deposit from creating a false sense of financial security.
The IRS’s 2026 Publication 505 explains that federal income taxes operate on a pay-as-you-go basis.
People who receive income without sufficient withholding, including certain self-employed individuals and royalty recipients, may need to make estimated tax payments.
The general estimated-tax rules can involve a $1,000 expected balance due after withholding and credits, alongside the applicable percentage tests. The precise calculation depends on the taxpayer’s circumstances.
Read IRS Publication 505 for 2026.
Now create a separate line in your household cash-flow sheet:
Money received but not yet available for spending.
Do not invent a universal tax-reserve percentage. Your federal tax position depends on the household’s total income, deductions, filing status, withholding, and other circumstances.
Instead, ask a qualified tax preparer to calculate an appropriate reserve.
If you are a contractor, bring your business income and expense records.
If you receive royalties, bring your royalty statements and ownership information.
Use this script:
“My household has variable income from oilfield-related work and may also receive mineral royalty income. Could you estimate our 2026 federal tax obligation, explain any estimated-payment requirements, and help us establish a reserve that doesn’t rely on guessing?”
Diagnostic if-then:
If your income is relatively steady, a regular estimated-tax calculation may be sufficient.
If payments are highly irregular, ask whether the annualized income installment method is appropriate.
If you have both W-2 wages and self-employment or royalty income, ask whether adjusting wage withholding could simplify your payments.
The objective is to prevent a strong month from becoming a financial headache several months later.
The financial trade-offs: What does oil wealth really cost?
Let’s bring the different pieces together.
Daniel’s family may have several financial responsibilities competing for the same dollars.
There is the household budget, business equipment, insurance, possible property taxes, federal taxes, savings, and future college costs.
A royalty payment might help with some of those obligations. Contractor income might help with others.
But neither is a guarantee of future financial security.
The most useful way to understand the problem is to separate the different sources of money and the obligations attached to each.
Table: The difference between visible oil wealth and household financial reality
| Financial item | What it tells you | What it does not tell you |
|---|---|---|
| County oil production | How much oil was reported produced | What a particular family earned |
| Mineral ownership | Whether someone owns an economic mineral interest | How much royalty income they will receive |
| Royalty statement | Payment details for a particular interest and period | Future guaranteed income |
| Contractor invoice | Revenue billed for work | Final business profit |
| Appraisal notice | A property’s assessed market value | Available cash in the household |
| Property-tax bill | Tax liability for the applicable account | Whether the property generates enough income to pay it |
| Bank deposit | Cash received | How much is safe to spend |
There is another cost worth discussing: uncertainty.
Oil prices change. Production can change. Equipment breaks. Customers pay late. Mineral interests can be divided among multiple owners. Family property can have complicated title histories.
Those things don’t necessarily mean that owning mineral rights is a bad investment or that working in the oil industry is financially unwise.
They mean that a household should not confuse a good year with permanent prosperity.
And there is a difference between earning a lot of money and building a life that can survive when the money slows down.
A closer look at Loving County’s property-tax figures
The September 2026 county notice provides an opportunity to understand the mechanics without pretending to know Daniel’s actual bill.
The proposed county rate moved from $0.47486 to $0.64639 per $100 of taxable value.
The following is a mathematical illustration of that proposed county-rate component only.
| Taxable value | At $0.47486/$100 | At $0.64639/$100 | Difference |
|---|---|---|---|
| $100,000 | $474.86 | $646.39 | $171.53 |
| $250,000 | $1,187.15 | $1,615.98 | $428.83 |
| $500,000 | $2,374.30 | $3,231.95 | $857.65 |
These figures are calculations based on the published proposed county rates, not verified final 2026 bills. They exclude other taxing jurisdictions, exemptions, changes in taxable value, and any other applicable adjustments.
The point isn’t that Daniel necessarily owes any of those amounts.
The point is that the difference between a proposed rate and an actual tax bill matters.
A property owner should always verify the final adopted rates and account-specific taxable value before budgeting.
The Texas Comptroller’s Loving County tax directory provides official appraisal-district and tax-office contact details.
The part nobody should overlook: A large asset can still create a cash-flow problem
Let’s return to Daniel.
Suppose his family owns a property with a mineral interest. Suppose it produces royalty income. Suppose the household receives a sizeable payment.
It would be tempting to treat that money as a financial victory.
But there are several questions he should ask before making a major decision.
Does the royalty income represent a temporary increase or a sustained pattern?
Is the family relying on one producing property?
Are the ownership documents clear?
Are there outstanding obligations attached to the property?
Does the household have sufficient reserves for taxes and business expenses?
Could the income decline while fixed household expenses remain unchanged?
Those questions are not pessimistic.
They are the difference between enjoying an income stream and becoming dependent on it.
The same applies if Daniel’s primary income comes from contractor work.
A strong month might justify replacing a critical piece of equipment. It might also be a good opportunity to replenish business reserves.
But using the entire payment to increase household spending could create problems when work slows.
This is not a call to live miserably while waiting for the next downturn.
It is a reminder that irregular income needs a different budgeting approach from a predictable salary.
If you want to explore the broader difference between gross income, actual take-home money, and household spending, read our AmeriCurious analysis of the hidden cost of working more to afford convenience.
The same principle applies here: money that appears on a statement is not always money that can safely be spent.
What if the oil well stops producing?
This is the question that makes the whole conversation personal.
A household can become accustomed to receiving royalty income. A contractor can become accustomed to a steady flow of work.
Then circumstances change.
Production declines. A well becomes less productive. A lease changes. An operator adjusts its activity. A customer delays a project.
The income that once felt dependable becomes uncertain.
There is no honest way to predict an individual Loving County property’s future production from the countywide July 2026 production report.
The county report tells us what was reported across the county for a particular month. It does not guarantee future output from a particular lease or well.
For Daniel, this means resisting the temptation to make long-term household commitments based on one unusually strong year.
A useful household exercise is to calculate three scenarios:
- Normal year: What does the household need if income continues at its recent average?
- Slow year: What happens if contractor revenue or royalty income declines?
- Disruption year: How long can the family meet essential expenses if a major customer, project, or income stream disappears?
These are planning scenarios, not predictions.
A financial adviser or accountant can help build them using actual household statements.
The most important number is not the largest payment Daniel has ever received.
It is the amount of money his family needs to remain financially stable when the next payment is smaller.
A few questions worth asking before making a financial decision
If you live in Loving County, own property, or work in the surrounding oil economy, these are reasonable questions to put on your list.
Does owning a home or ranch automatically mean I own the minerals?
No. Surface and mineral estates can be separated. Check the deed and recorded ownership history.
Are oil and gas royalties taxable?
Generally, yes. The IRS classifies royalties from oil, gas, and mineral properties as ordinary income in most cases. Reporting and deductions depend on the ownership and operating arrangement.
Can mineral properties be subject to property taxes?
Yes. Mineral interests can be included in the property-tax appraisal system. The appraisal and the actual royalty payments are separate financial matters.
Can I challenge an appraisal?
Texas property owners have protest rights when qualifying appraisal decisions or records are disputed. Form 50-132 is the standard Property Owner’s Notice of Protest.
Does a large oil production number mean local families are wealthy?
No. Countywide production does not reveal how mineral ownership is distributed, how much royalties are paid to particular owners, or what local households retain after expenses and taxes.
Where should I begin if I am uncertain about my Loving County property account?
Start with the Loving County Appraisal District at 114 W. Collins Avenue in Mentone, telephone (432) 377-2201. For ownership questions, obtain the recorded deed and consult a qualified Texas title or oil-and-gas professional.
Daniel’s real financial question isn’t how much oil is underground
By now, Daniel has a better way to think about the problem.
He doesn’t need to compare his household with the biggest royalty recipient in the county.
He doesn’t need to assume that every contractor is making a fortune.
And he certainly doesn’t need to make a financial decision just because the latest production statistics look impressive.
What he needs is a clear picture of what his family owns, what it earns, what it owes, and what it can reasonably expect to keep.
That may involve reading an old deed, examining a royalty statement, questioning an appraisal, or sitting down with a tax professional.
It may also involve accepting that his family’s financial future depends more on the quality of its decisions than on the amount of oil produced nearby.
There is nothing wrong with being proud of making a living in an economically important county.
There is nothing wrong with wanting to benefit from the opportunities around you.
But there is a quiet kind of financial freedom in knowing that your family’s security doesn’t depend on confusing someone else’s mineral wealth with your own.
The micro-win: One document, ten minutes, a clearer picture
Don’t try to solve your entire financial future tonight.
Take ten minutes.
Find the latest deed or property document for your Loving County property.
Write down one question:
Does my ownership include the mineral estate, the surface estate, or both?
If you cannot answer that question confidently, that’s your first task.
You don’t need a new investment strategy, an expensive financial app, or another motivational podcast.
You need a verified answer.
And that is a perfectly good place to start.
Take-home message
Loving County’s oil production is extraordinary. Its mineral-property values are substantial. Its economic activity is far bigger than its permanent population might suggest.
But financial security is personal.
A royalty owner, a surface landowner, and an independent contractor can all participate in the same oil economy and have completely different financial lives.
The lesson is not to chase oil wealth.
It is to understand ownership, separate gross income from spendable money, prepare for taxes, and make decisions based on what your household actually controls.
If this article made you look at your own financial situation differently, I’d love to hear your perspective.
- Like this article if you found the distinction between mineral ownership and surface ownership useful.
- Comment: Do you think people outside the oil industry understand how mineral rights actually work?
- Share this article with someone who owns property or works in the Permian Basin.
- Subscribe to AmeriCurious for more deeply researched stories about the money, people, and everyday realities shaping American communities.
- Bookmark this guide if you want to revisit the property-tax and royalty-income checklist.
“A place can be rich in resources without every person who calls it home being rich in opportunity.”
Until next time, stay curious. Stay informed. And never confuse a big number with a secure future.
AmeriCurious