For SAVE borrowers who got the 90-day notice, panic-chose RAP, and now have a first payment due this month. Educational content, not financial or legal advice. Verify your notice, balance, and PSLF count at StudentAid.gov’s official RAP page before you act.
I am an idiot. I chose RAP on September 15th because I was scared and stressed and freaking out — as we all are. I thought RAP was supposed to replace SAVE so it should’ve been ok, right? Wrong. $820 a month.
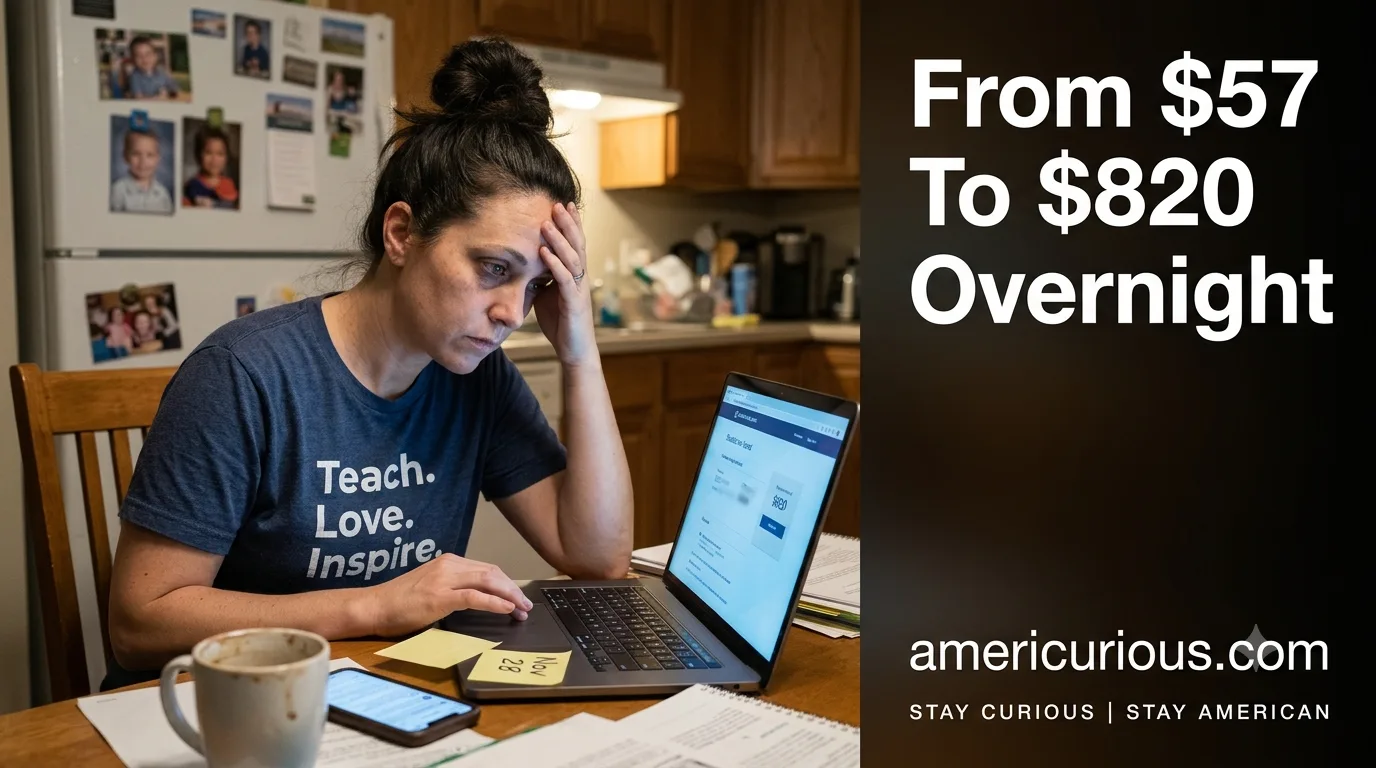
It’s 2:00 AM in Fort Worth. Not the pretty kind of quiet. The kind where the AC hums too loud, my husband is at work on nights, the kids are finally asleep, and I’m at the kitchen table in a t-shirt that says “Teach. Love. Inspire.” with a laptop that is at 14% battery.
My Nelnet portal says first payment due November 28.
$820.
My SAVE payment was $57.
I keep refreshing the page like it will change its mind.
If you are reading this with your phone glow on your face in bed, I see you. You are not behind. You are not lazy. You are exactly where millions of us are — terrified and paralyzed, unsure what to do, and scared that one wrong click will erase 12 years of teaching.
This post is for you. Not for “borrowers” in general. For you, tonight.
I’m AmeriCurious. I’m not your financial advisor. I’m the person who sat on hold, ran the math three different ways, and wrote it all down so you don’t have to do it at 2AM with a fried brain.
Let’s do this together, in 10 minutes at a time.
Pull Quote: “I am an idiot — SAVE plan fiasco. Mine went from $300 IBR to $57 SAVE to $820 RAP!! First payment is due 11/28/26. I am so stressed out!”
— The exact panic post flooding r/StudentLoans in October 2026, and the sentence Jessica has said to herself every night since September
Care to Read?
9 Sneaky Money Habits That Are Keeping You Broke
You Have Already Tried Everything. That’s Why You’re Here.
Before I give you anything new, I need to clear the slate. Because if I just hand you a checklist, your brain will rightly say: I’ve heard this before.
You have.
You called your servicer. Not once. Three times. Rep one said “do nothing, you’re fine.” Rep two said “switch now or you’ll be placed in Standard.” Rep three read a script about RAP being “best for many borrowers” and hung up. You were on hold for two hours. The callback feature never called back. One teacher in a public report left her phone on all day while teaching because that was the only way to get through to MOHELA.
That didn’t fail because you asked the wrong question. It failed because the system is designed to deflect you. Borrowers have documented average waits of two hours, transfers to supervisors who send you back to an automated line, and advanced reps who actually know the difference between IBR versions. You weren’t unprepared. You were put in a loop.
You tried the StudentAid.gov simulator. It showed you IBR estimates, but RAP wasn’t even an option when you looked in September. The simulator lagged behind the law. RAP only launched July 1, 2026, and the tools didn’t catch up. Of course the numbers didn’t match your servicer quote. They weren’t measuring the same thing.
You fell down a Reddit rabbit hole. 200 comments. 14 screenshots saved. One person says “do nothing until the last moment.” Another says “switch now, sooner you switch sooner you pay.” Another swears SAVE forbearance months count for PSLF. Another swears they don’t. You closed the app more confused than when you opened it.
Reddit didn’t fail you because people are lying. It failed because everyone is working from a different notice date, a different servicer, a different AGI, and a different PSLF count. Your situation is not their situation.
You watched the YouTube video. The creator was single, no kids, no PSLF, making $85k. His RAP math looked great. Yours doesn’t, because you file jointly, you have two dependents, and you have 104 PSLF payments on the line. His video wasn’t made for a married Texas teacher.
You listened to the TikTok that said “File separately and save $800!” It didn’t mention you would lose the student loan interest deduction, child-related credits, or IRA room. It didn’t mention the tax cost could eat the RAP savings. It was a loophole without the fine print.
You asked your union rep / coworker. “Just pick RAP, it’s the new SAVE.” I get why they said it. They were trying to help. But RAP is not SAVE. SAVE protected 225% of the poverty line before it calculated your payment. RAP protects none of your income. It takes 1% to 10% of your whole AGI. For a lot of us, that is a completely different universe.
None of that was your fault. This feels like a personal failure, but the data tells a completely different story.
Brookings modeled RAP against the old REPAYE plan and found payments are nearly identical for middle-income borrowers but diverge sharply at the edges — very low-income borrowers who used to pay $0 now owe at least $10, and higher earners pay more, with no cap tied to the 10-year Standard payment. The Congressional Budget Office expects RAP to raise $271 billion over 10 years, $150 billion of it from higher repayments by existing borrowers.
You are not broken. You are in a system that was intentionally made more expensive and more confusing, and then you were given 90 days to figure it out while teaching full-time and raising kids.
That is not a discipline problem. That is a design problem.
And you are not alone in it. That is the validation I needed at 2AM, and maybe you need it too.
The 90-Day Notice, Decoded in Plain English
Let’s translate the email you got, because the email was not written for a tired human brain.
The One Big Beautiful Bill Act — OBBBA — was signed July 4, 2025. Its student loan changes took effect July 1, 2026, as FAFSA Updates’ July 1, 2026 effective-date guide lays out in one timeline. RAP launched that same day as the new income-driven plan.
SAVE ended by court order on March 10, 2026. Borrowers in SAVE administrative forbearance started getting 90-day notices in waves starting July 1, 2026. As SaveToRAP’s servicer notice tracker shows, MOHELA notified July through October 2026, Nelnet and Aidvantage through the end of 2026. The Department compressed the schedule — if you thought you had until “sometime next year,” that window closed.
Your 90 days start from your notice date, not July 1. Find it. Screenshot it. That date controls everything.
If you do nothing by the end of your 90 days, you do not stay in SAVE. You are auto-placed. For most SAVE borrowers, that means the Tiered Standard Plan or RAP, depending on your loans. And here is the part that made my stomach drop when I learned it:
The new Tiered Standard Plan never counts toward PSLF. Not at the 10-year tier. Not at any tier. As District Capital’s PSLF in 2026 guide puts it, if you are pursuing PSLF, never sit in Tiered Standard. It is the default for new borrowers and a common SAVE-exit landing spot — and it earns zero PSLF credit.
RAP does count toward PSLF. IBR does count. PAYE and ICR count through June 30, 2028, then sunset. SAVE payments you actually made count. SAVE forbearance months do not — unless you buy them back, and that price changed in 2026. We’ll get there.
Now that we know the mechanism behind the glitch — a 90-day clock, a default that kills PSLF, and a new plan that looks like SAVE but isn’t — here is how we systematically dismantle it, one small experiment at a time.
But first, you need to see RAP for what it actually is.
RAP in Plain English: The 1% to 10% Trap
RAP is not SAVE with a new name. Think of it like this: SAVE was a sponge that protected the first chunk of your income, then squeezed a percentage out of what was left. RAP is a flat tax on your whole paycheck, with a small thank-you note attached.
Under RAP, your payment is a percentage of your total adjusted gross income — AGI, line 11 of your 1040 — divided by 12, minus $50 for each dependent you claim, with a $10 minimum. The percentage steps up 1 point for every $10,000 of AGI, from 1% at the bottom to 10% above $100,000. That formula is spelled out in RAP Loan Calc’s Federal Student Aid formula breakdown and in the regulation itself.
Two subsidies are real, and they matter:
- Interest waiver: If your payment doesn’t cover the interest that month, the unpaid interest is not added to your balance. Your loan can’t grow from unpaid interest as long as you make your required payment.
- Principal match: Up to $50 of your payment is credited toward principal, even if it doesn’t cover interest. Your balance is guaranteed to go down at least $50 a month when you pay on time.
Forgiveness after 30 years — 360 payments. Not 20. Not 25. Thirty. And in 2026, income-driven forgiveness is potentially taxable again. PSLF forgiveness remains tax-free. That difference alone can be tens of thousands of dollars.
Table 1: RAP vs. SAVE vs. IBR — Why Your Payment Jumped
Caption: SAVE protected 225% of poverty; IBR protects 150%; RAP protects 0%. That one difference explains most $57 → $820 jumps.
| Feature | SAVE (ended Mar 10, 2026) | IBR (new, post-2014 loans) | RAP (launched July 1, 2026) |
|---|---|---|---|
| Payment base | 5%–10% of discretionary income (above 225% poverty) | 10% of discretionary income (above 150% poverty) | 1%–10% of total AGI, no poverty protection |
| Minimum | $0 possible | Varies | $10 floor |
| Dependent credit | Family size in poverty formula | Family size in poverty formula | -$50/month per dependent claimed |
| Interest waiver | Yes | Subsidized only, first 3 years | Yes, all Direct Loans |
| Principal match | No | No | Up to $50/month |
| Forgiveness | 20 yrs undergrad / 25 yrs grad | 20 yrs (post-2014) | 30 years |
| PSLF counts? | Payments made yes, forbearance no | Yes | Yes |
| Tax on forgiveness | Taxable in 2026 | Taxable in 2026 | Taxable in 2026 |
Source: Britannica Money’s RAP vs. SAVE comparison table and Federal Student Aid RAP brackets.
Read that middle row again. SAVE said: “We won’t charge you on the first $35,000 or so.” RAP says: “We charge you on dollar one.” For Jessica, with joint AGI of $92,000, that is the difference between a $150 SAVE payment and an $820 RAP payment.
This sounds like standard “RAP is more expensive” advice, which usually makes me roll my eyes too. But look at what happens when you run her numbers, not a generic table. The generic table hides the married-filing trap. Her numbers expose it.
Her Math, Three Ways: The Joint Filing Trap
Jessica’s joint AGI is $92,000. Her husband makes $38,000. She makes $54,000. They have two dependents.
On RAP, joint AGI puts them in the 9% bracket. $92,000 × 9% ÷ 12 = $690, minus $100 for two dependents = $590… but her servicer quoted $820 because her balance and interest and the exact bracket calculation pushed it higher, and because she had capitalized interest from SAVE forbearance. The point is not the exact $820. The point is the jump.
If she filed separately, RAP would use only her $54,000 AGI — 5% bracket — minus dependents she claims. That drops the payment to roughly $600 in the real posts I’ve seen: “Mine went from $388 SAVE to $1,430 RAP joint. If I switch to filed separately, it becomes $600 RAP.”
IBR, joint, might be $740. IBR, separate, might be $800. The cheapest loan payment is not always the cheapest total cost.
Table 2: Jessica’s Three-Way Math (Illustrative, Using Her Real AGI)
Caption: Filing separately can slash the RAP payment, but you must subtract the tax cost before you decide. Run both ways.
| Scenario | AGI Used | Est. Monthly Payment | PSLF Counts? | Hidden Cost |
|---|---|---|---|---|
| RAP, Married Filing Jointly | $92,000 joint | ~$820 | Yes | 30-year clock, taxable forgiveness |
| IBR, Married Filing Jointly | Discretionary income, joint | ~$740 | Yes | 20-year clock, taxable forgiveness |
| RAP, Married Filing Separately | $54,000 hers only | ~$600 | Yes | Lose student loan interest deduction, some credits, IRA room — must run tax comparison |
That last row is where TikTok lies by omission. As FinCalcApp’s RAP calculator FAQ on married filing separately warns, MFS gives up the student-loan interest deduction, restricts IRA contributions, and disqualifies you from several credits. Sometimes the lost credits outweigh the RAP savings. Sometimes they don’t. You cannot know without running joint vs. separate tax side-by-side.
If your environment makes a full tax overhaul impossible tonight — and it does, you have 10 minutes, not 10 hours — don’t force it. Let’s pivot to a psychological lever instead: test one variable for three days, get data, then decide.
That is the whole philosophy of this post. These are not prescriptions. They are behavioral experiments. If a tool fails, it is not because you failed. It is data. It tells you where your friction actually lives.
Pick the experiment that matches your energy right now.
PSLF: The 104 Payments You Cannot Afford to Lose
Jessica has 104 qualifying payments. She needs 16 more.
That number is her whole identity as a teacher who stayed. It is also the most fragile part of this transition.
Here is what counts and what doesn’t, as of October 2026:
- IBR payments count. RAP payments count. PAYE/ICR payments count through June 30, 2028.
- SAVE payments you actually made count. SAVE forbearance months — the months you were in administrative forbearance through no fault of your own — do not count automatically.
- Tiered Standard payments never count. Ever.
- Buyback exists, but it got more expensive. On March 31, 2026, the Department stopped using SAVE amounts to price SAVE-era buyback months. As Tate Law’s PSLF Buyback guide explains, if you were in SAVE on or after July 18, 2024, the price is now based on the plan you were in before SAVE — usually IBR, PAYE, or ICR math. For many borrowers, that is substantially more.
Jessica’s question is not “should I buy back?” It is “what will buyback cost me, with my pre-SAVE IBR payment, and will it get me to 120 faster than just paying RAP for 16 more months?”
No competitor article answers that with her numbers. The calculator sites don’t ask about PSLF. The law explainers don’t show buyback pricing.
So we will.
And if you are not on PSLF — if you are on RAP for income-driven forgiveness in 30 years — your experiment is different. You are testing whether RAP’s interest waiver + $50 principal match actually makes your balance decline, or whether IBR’s 20-year clock is cheaper even with a higher monthly payment. Same toolkit, different variable.
The Playbook: Three Experiments, Not a 5-Step Checklist
Don’t try to build this entire system today. Instead, pick just one variable to test in the next ten minutes. The ultimate win is not executing all of this perfectly. The win is walking away with one tool that fits your life.
Experiment 1: The Immediate Micro-Fix (Tonight, 10 Minutes)
If you have 10 minutes right now, do this. If you have 2 hours, skip to Experiment 2.
This is for the 2AM brain. No tax overhaul. No servicer call. Just stop the bleeding and get a screenshot you can trust.
Hypothesis to test: If I lock down my notice date, PSLF count, and three payment estimates tonight, I will wake up less paralyzed tomorrow.
Exact steps:
- Open StudentAid.gov in a private tab. Log in. Screenshot: servicer name, balance, interest rate, IDR payment count, PSLF qualifying payment count. Save to Photos with date.
- Find your 90-day notice email from ED and your servicer. Screenshot the deadline date. Write it on a sticky note: “My deadline is ____, 2026.”
- Open the RAP calculator at Student Loan Sherpa’s RAP Calculator — it lets you toggle joint vs. separate AGI and dependents. Enter your last 1040 line 11 AGI. Screenshot all three scenarios: RAP joint, RAP separate, IBR joint.
- Do not click “apply” yet. You are collecting data, not committing.
If-Then troubleshooting:
- If the simulator doesn’t show RAP, use the Sherpa calculator above — it uses the official FSA formula. Your servicer quote is still the final word, but the calculator is closer than the lagging simulator.
- If you already chose RAP in panic (like Jessica on Sept 15), do not panic again. You can request a plan change. The next experiment shows you how.
Exit strategy for this experiment: If screenshots make you more anxious, stop after step 2. You have your deadline. That alone is a win. Come back tomorrow.
Experiment 2: The Environment Shift (This Week, 28 Minutes on Planning Period)
If you thrive on accountability and can make one call, do this. If calls make you shut down, skip to Experiment 3.
This is the servicer survival guide. You need one documented conversation with an advanced rep, not three undocumented ones with front-line reps.
Hypothesis to test: If I call with a script and ask for an advanced rep, I will get a written confirmation I can trust.
Exact script — say these literal words:
“Hi, I’m a SAVE borrower with a 90-day notice. My deadline is [date]. I have 104 PSLF qualifying payments. I need to confirm three things in writing: 1) Can I switch from RAP to IBR if I already selected RAP? 2) What is my exact IBR payment using my joint AGI? 3) What is my PSLF buyback price for SAVE forbearance months using my pre-SAVE plan? Please email me the confirmation. Can I speak with an advanced customer service representative?”
Why this works: Front-line reps often don’t know the difference between old IBR (15%) and new IBR (10%), or between RAP and Tiered Standard. Advanced reps do. Asking for them by name changes the call. Asking for email confirmation changes everything — you now have a record if they later say “we never told you that.”
Call tips from real borrowers:
- Call Nelnet at 1-888-486-4722 or MOHELA at 1-888-866-4352. When prompted for SSN, press through to “more options” — borrowers have documented that the human queue is buried 6-7 menus deep. Request a callback and stay on hold if you can; callbacks have failed.
- If you get a false “past due” notice — like the August 2026 MOHELA error where borrowers saw $11,000 past due they didn’t owe, as Forbes reported on the Senate investigation — screenshot StudentAid.gov showing forbearance and the servicer notice side-by-side. Do not pay the false amount. Email the servicer with both screenshots and ask for correction in writing.
If-Then troubleshooting:
- If you are on hold for 2 hours and get disconnected, you did not fail. The system failed. Try the email route: send the script above via your servicer portal message center. Portal messages create a paper trail and don’t require hold music.
- If the rep says “just consolidate,” say: “I understand consolidation after July 1, 2026 would lock me out of IBR. I am not consolidating. Please confirm my IBR eligibility without consolidation.” Consolidation after July 1, 2026 is a one-way door to RAP-only for all your loans.
User profile check: Introvert who loses energy from calls? You can do this experiment by portal message instead of phone. Same script, typed. The variable is the channel, not the content.
Experiment 3: The Cognitive Reframe (Before Nov 28, 15 Minutes)
If you already chose RAP and can’t undo it this week, or if you need to decide joint vs. separate, do this.
This is the decision experiment. You are not choosing forever. You are testing which plan you can actually afford for the next 16 PSLF months.
Hypothesis to test: If I compare IBR vs. RAP for my next 16 months of PSLF, not 30 years, I will see a finish line I can afford.
Exact tool: Make a simple table on paper. Three columns: RAP Joint, IBR Joint, RAP Separate. Rows: Monthly payment, × 16 months = total to PSLF, + buyback cost if needed, = total to finish line. Then add one row: “Tax cost of MFS (ask a CPA or run TurboTax joint vs. separate estimate).”
For Jessica: RAP Joint $820 × 16 = $13,120 to PSLF. IBR Joint $740 × 16 = $11,840. RAP Separate $600 × 16 = $9,600 + tax cost. Suddenly 30 years feels abstract, but 16 months feels doable — or not doable, and that is data too.
If you are not on PSLF: Change the row to “Total paid over 20 years (IBR) vs. 30 years (RAP)” and add “Taxable forgiveness amount.” RAP’s interest waiver means your balance at year 30 will be smaller, so your tax bomb will be smaller. IBR’s 20-year clock means you are done sooner but may owe tax on a larger balance. Neither is automatically better. It depends on your AGI trajectory.
If-Then troubleshooting:
- If filing separately saves $200/month on RAP but costs $250/month in lost credits, then MFS is not a lever for you. Drop it immediately. It means your friction is not filing status — it is AGI bracket. Your next experiment is IBR vs. RAP joint.
- If graduated plan looks cheaper ($93 starting), remember: graduated does not count for PSLF, and payments rise every 2 years. For a PSLF borrower, graduated is a trap. For a non-PSLF borrower with a small balance ($14k at 3.2%), graduated might be the cheapest path to payoff. Same tool, opposite conclusion depending on your profile. That is why we group by user profile, not by prescription.
The reframe: You are not “stuck on RAP for 30 years.” You are testing a 16-month bridge to PSLF, or a 20-year vs. 30-year tradeoff. You can switch plans again later (as long as you don’t take new loans or consolidate after July 1, 2026, which locks you to RAP-only). The door is not closed. The clock is just loud.
What OBBBA Did Not Change (So You Don’t Panic About Everything)
At 2AM, everything feels like it changed. It didn’t.
Undergraduate Direct Loan limits are unchanged. Pell Grant maximum is still $7,395 for 2026-27. PSLF itself was not eliminated — it is in statute, only Congress can end it, and Congress didn’t. As Stanford’s OBBBA loan changes page notes, existing borrowers enrolled before July 1, 2026 have legacy protections for up to 3 years on borrowing limits.
Parent PLUS caps ($20,000/year, $65,000 lifetime) and Grad PLUS elimination are real, but they affect new borrowing, not your existing SAVE loans. If you are not taking a new loan or consolidating after July 1, 2026, you keep IBR eligibility. That is the line in the sand. Do not cross it without running the math.
Knowing what didn’t change is not optimism. It is triage. You only have to solve the 90-day plan choice. Not the entire student loan system tonight.
FAQ: Direct Answers for Your 2AM Brain
1. Can I switch from RAP to IBR after I already chose RAP?
Yes, if all your loans were disbursed before July 1, 2026 and you have not taken new loans or consolidated on/after that date. Request a plan change via StudentAid.gov or your servicer, and get email confirmation. If you have taken new loans after July 1, 2026, you are RAP-only for income-driven repayment.
2. Do SAVE forbearance months count toward PSLF?
No, not automatically. Payments you made under SAVE count. Forbearance months do not, but you can request PSLF buyback. Since March 31, 2026, buyback for SAVE months is priced off your pre-SAVE plan, not SAVE — so it costs more than it used to.
3. Does Tiered Standard count for PSLF?
No. Never. If you do nothing and are auto-placed in Tiered Standard, you earn zero PSLF credit. That is why you must actively choose IBR or RAP if you are pursuing PSLF.
4. Is RAP cheaper than IBR?
Depends on your AGI, dependents, and filing status. At $50k AGI single, RAP and new IBR are nearly tied (~$208 vs. $217). At $95k AGI with dependents, IBR is often much cheaper because RAP has no poverty protection and no cap. Run both with your exact AGI.
5. Should I file married filing separately to lower RAP?
Maybe, but only if the RAP savings exceed the tax cost. MFS loses the student loan interest deduction and restricts other credits. Run joint vs. separate tax estimates side-by-side before you decide. Do not decide on the loan payment alone.
6. What is the $50 principal match?
If you pay on time under RAP, up to $50 of your payment is credited to principal, and unpaid interest is waived. Your balance is guaranteed to decline at least $50/month. It does not mean your payment is $50 cheaper — it means your balance moves in the right direction.
7. Will RAP forgiveness be taxed?
PSLF forgiveness is tax-free. Income-driven forgiveness (IBR or RAP after 20/25/30 years) is potentially taxable in 2026 because the temporary exemption expired Dec 31, 2025. Factor that into a 30-year RAP decision.
8. What happens if I miss my 90-day deadline?
You will be auto-placed in a standard plan (Tiered Standard for new loans, or RAP/IBR for eligible old loans depending on servicer guidance). For PSLF borrowers, auto-placement in Tiered Standard is the worst outcome because it earns no credit. Do not let the deadline pick for you.
Your Take-Home: One Tool, Tonight
You don’t need to solve OBBBA tonight. You don’t need to overhaul your taxes, call your servicer for two hours, or decide between 30 years and 20 years while your kids sleep in the next room.
You need one tool that fits your life.
If you have 10 minutes, screenshot your deadline, your PSLF count, and your three payment estimates. That is your micro-win. That is data, not failure.
If you have 28 minutes this week, send one portal message with the script above and ask for email confirmation. That is your environment shift.
If you have 15 minutes before November 28, run the 16-month PSLF math. That is your finish line.
Pick one. Test it for three days. If it feels too heavy, drop it immediately — it means your friction lives somewhere else, and that is useful information, not a character flaw.
Jessica’s story is not finished. She still has a payment due November 28. She still has 16 PSLF payments to go. But she no longer has to do it blind, at 2AM, with a dead laptop battery and a $820 surprise.
She has a deadline on a sticky note. She has a script. She has a table. She has a finish line she can see.
You can have that too.
Your literal first step right now: Open StudentAid.gov, screenshot your PSLF qualifying payment count, and write your 90-day deadline on a sticky note. Do that one thing. Then close the laptop. Then sleep.
Tomorrow, we run the math together.
Share This With One Person Who Got the Same Email
If this helped you feel less alone at 2AM, please like, comment, and share this post with one coworker, one Facebook group, or one r/PSLF thread where someone is freaking out tonight. Bookmark it for your 90-day deadline. Subscribe to AmeriCurious for the next OBBBA update — Parent PLUS caps, Grad PLUS, and the July 2028 sunset are coming, and we will decode them the same way: in plain English, with your numbers, not a generic table.
Comment below: What was your SAVE payment, and what is your RAP quote? What is your PSLF count? I read every comment, and your numbers help the next borrower see they are not alone.
“You are not an idiot for panic-choosing. You are a teacher who stayed, who made 104 payments, who is trying to protect her family in a system that changed the rules mid-game. The win is not a perfect plan. The win is one clear tool, used tonight, that gives you back your sleep.”
— AmeriCurious
Founder, americurious.com | Covering OBBBA and federal student loan changes for American borrowers, in plain English, with evidence.
Sources: Brookings — How OBBBA Reshapes Student Lending, Key — OBBBA and Student Loans, FAFSA Updates — OBBBA In Effect July 1, 2026, SaveToRAP — Servicer Notice Timeline, District Capital — PSLF in 2026, Tate Law — PSLF Buyback, Forbes — MOHELA False Delinquency Investigation, Stanford — OBBBA Loan Changes. Last updated November 10, 2026. Educational content only — verify at StudentAid.gov.