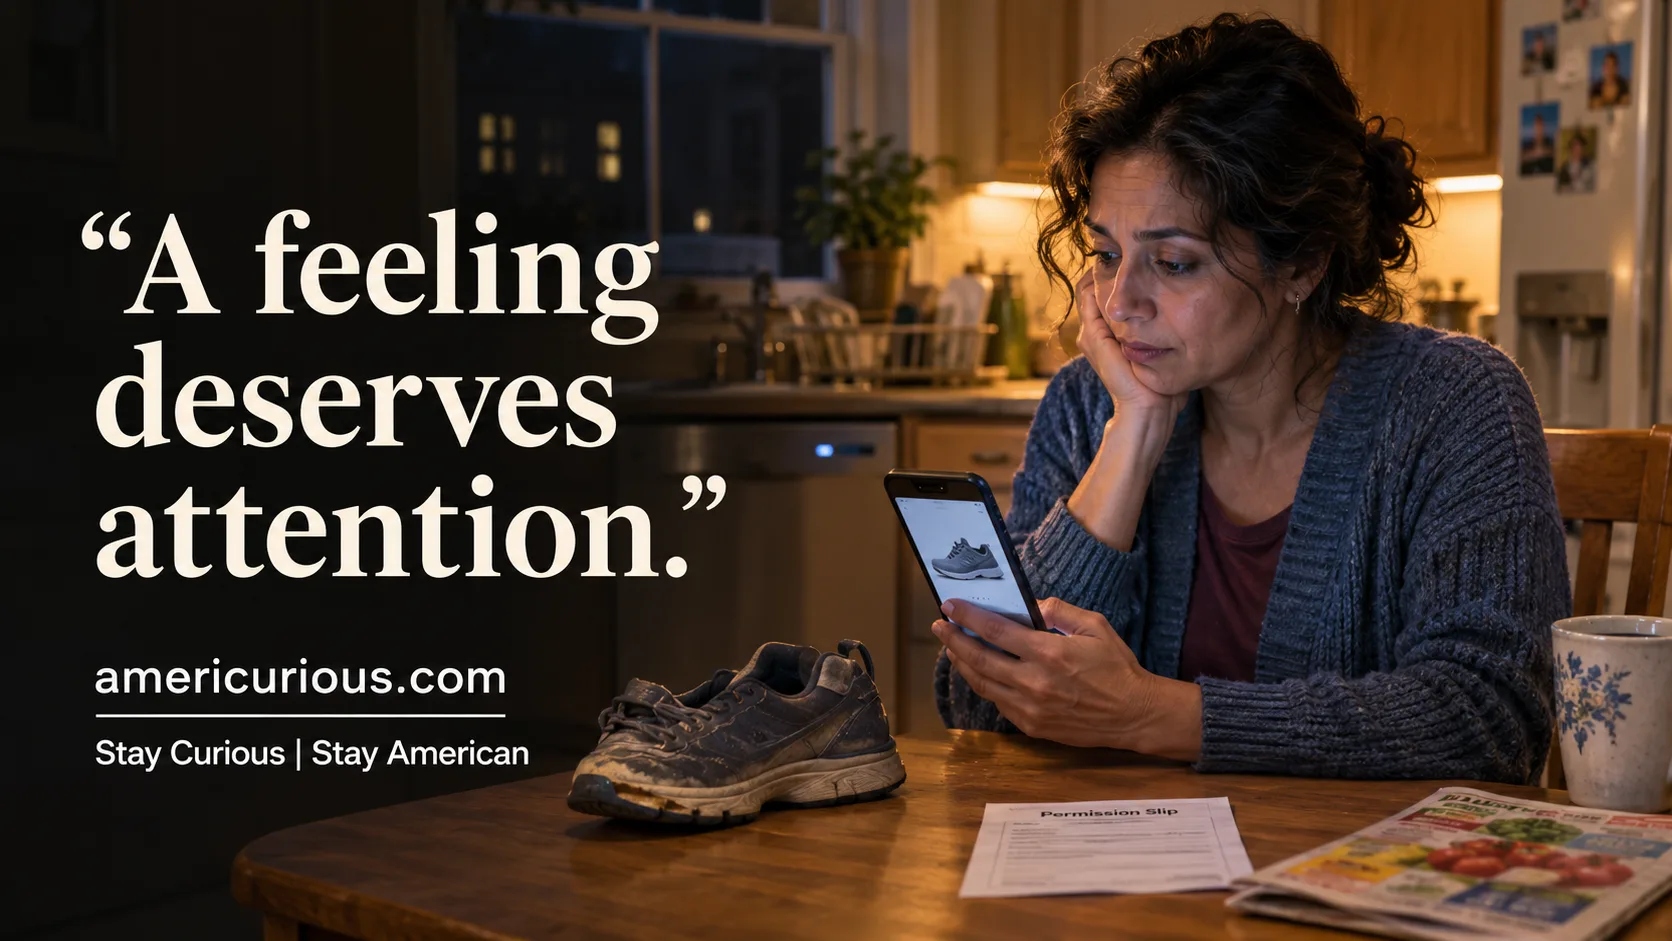
Feel guilty buying things for yourself while supporting family? Learn how to check the numbers, share the load, and make a decision without shame.
By AmeriCurious
Guilt about spending money on yourself can come from real financial pressure, uncertainty, or a sense that family needs must always come first. Start by checking what is actually available after upcoming obligations. Then decide whether the purchase fits—not whether you have earned the right to need something.
At 8:43 p.m., Maya sits at her kitchen table with a pair of $38 walking shoes open on her phone. The sole of her old pair is peeling. The dishwasher hums; her son’s permission slip waits beside an unopened grocery flyer.
A text from her mother appears: “Can you take me to the pharmacy Saturday?”
“Of course,” Maya types.
Then she looks back at the shoes. Her shoulders tighten. If I buy these and Mom needs help paying for something, I’ll have to say no.
Her partner notices the screen. “Are those the shoes you needed?”
“They can wait,” Maya says, closing the tab.
She hasn’t checked the bills due before payday. She doesn’t know whether her mother will need financial help at the pharmacy. But the shoes already feel like a decision against her family.
Maya is a fictional composite. Her scene illustrates a situation; it is not a reported interview.
Related Reading….
How to Make Your First $10,000 as a Teen (3 Simple Steps)
Why do I feel guilty spending money on myself?
You may feel guilty because a purchase for yourself competes, in your mind or in your budget, with someone else’s needs.
Sometimes the conflict is concrete: the money is needed for rent, groceries, medication, or a bill due tomorrow. Sometimes the cost is uncertain, and your mind supplies a list of possible emergencies. And sometimes the numbers allow a purchase, but the thought of putting yourself on the list still feels uncomfortable.
More than one of these can be true at once.
In a 2026 Ally-sponsored YouGov survey, 72% of more than 5,000 U.S. adults with a role in household financial decisions reported at least some guilt when spending on joy instead of other financial goals. The question was about joy and financial goals—not specifically family caregiving—so it cannot tell us how many people feel exactly what Maya feels. The survey relied on self-reports and was sponsored by a bank. [1]
Family responsibilities can add a real financial dimension. In AARP’s 2026 study of 2,538 U.S. adults caring for an adult relative or friend, respondents reported an average of $11,508 a year in out-of-pocket caregiving costs. An average is not a bill for every caregiver; expenses and circumstances vary. [2]
Real families’ experiences also differ. NPR reported that Meghan Maher reduced her work hours and then left her job while caring for her mother and young child. USA TODAY reported that Florida caregiver Deanna Adkins filed for bankruptcy after family care and other expenses contributed to unmanageable debt. Neither account proves what will happen to another family. [3] [4]
Maya’s conflict has two parts: What can the household afford? And what does she believe it means to spend on herself? A useful response has to leave room for both.
A feeling deserves attention. It does not have to make the entire decision.
Is it guilt or a real financial warning?
It can be both, so check the numbers before trying to talk yourself out of the feeling.
A bank balance alone may not show what is available. Some of it may already be needed for a bill, food, transportation, or a family expense you expect before the next paycheck. On the other hand, a purchase is not automatically reckless just because it benefits you.
Table: A practical way to sort the decision
| What you find | What it might mean | A reasonable next step |
|---|---|---|
| The purchase would leave a known essential unpaid | The concern points to a real tradeoff | Pause, explore alternatives, and seek support if needed |
| You cannot estimate upcoming costs | The decision is uncertain, not necessarily wrong | List what is known and set a time to revisit |
| The purchase fits your current plan, but you still feel ashamed | The feeling may need attention alongside the math | Try a kinder, more specific response to the guilt |
| Another person controls access to money or retaliates over spending | The issue may involve safety or control | Seek private support; do not assume a joint discussion is safe |
This is a decision aid, not a financial test or diagnosis. A need can be urgent even when the money is not there, and an affordable purchase can still be one you choose not to make.
In Maya’s case, the $38 price is only one piece of the picture. She also needs the dates and amounts of the next bills, expected income, and any caregiving costs she already knows about. Until then, neither “buy them” nor “you can’t afford them” is an honest conclusion.
What can I do when I feel guilty spending money on myself?
Start with a short money check, then choose one next action rather than trying to solve every possible family expense at once.
The steps below are practical adaptations of financial tools and behavioral research. They have not been proven as a package to eliminate self-spending guilt. Use what fits; leave what does not.
1. Make a “before next payday” picture
A short cash-flow picture gives the decision a starting boundary: what must happen before more money comes in?
The Consumer Financial Protection Bureau’s toolkit offers bill calendars, spending trackers, cash-flow tools, and tools for prioritizing bills. These are planning aids, not evidence that a particular purchase is safe or that tracking will remove guilt. [5]
Set aside ten minutes and write down:
- The money currently accessible to the household.
- Income expected before the next payday.
- Bills due in that period, including their dates.
- Estimated essentials, such as food and transportation.
- Known family-care costs, plus any amount deliberately set aside for an uncertain one.
Then compare what remains with the full purchase price, including tax or delivery. Avoid counting money twice. If an important amount is unknown, write “unknown” rather than pretending it is zero.
Maya checks the bills with her partner. They can see what is due before payday, but they do not yet know whether her mother’s pharmacy visit will involve an extra cost. Maya decides to ask before making the shoe decision.
A short window is a starting point, not the whole financial picture. If a large bill comes due just after payday, or income is irregular, include it before deciding what is available.
Script: “I’m not deciding whether I deserve this yet. I’m checking what the next two weeks need.”
Two-minute starter: Write the next payday and the next bill due on a piece of paper.
Obstacle and fix: If opening every account feels overwhelming, start with the account used for bills and add the rest later.
Track it: Note whether you made a decision with the relevant dates in front of you.
When it may not work: If the available money will not cover essentials, a clearer list cannot create income. Move to the support step rather than forcing a personal-spending amount.
2. Replace the verdict with a fair question
Self-compassion means responding to difficulty without adding an attack on your character. It does not require pretending a purchase is affordable.
A 2021 meta-analysis by Wakelin and colleagues included 19 papers involving 1,350 participants and found that self-compassion-related interventions reduced self-criticism compared with control conditions. The studies varied, their quality was moderate, and the review did not test Maya’s specific money decision. A single sentence is not the same intervention studied in that review. [6]
Try this sequence when the thought “I’m selfish” appears:
- Name the concern: “I’m worried about what my family may need.”
- Name your need without arguing that it outranks anyone else’s.
- Ask a concrete question: “Does this fit what we know about the next pay period?”
- Allow the answer to be yes, no, or “I need more information.”
Maya might say, “I care about Mom’s costs, and my shoes need replacing. I can check both.” That sentence does not purchase the shoes. It gives her a fairer way to investigate.
Script: “Having a need is not the same as neglecting someone else.”
Two-minute starter: Write the harsh thought, then rewrite it as a question you can answer.
Obstacle and fix: If kind language feels forced, use neutral language: “This is a $38 decision with an unknown expense.”
Track it: Record whether your response names a fact or a question rather than a judgment about your worth.
When it may not work: Persistent, intrusive guilt or distress may need more than a self-help exercise. A licensed mental health professional can help you explore it without assuming all financial concerns are irrational.
3. Put a limit on the unknown—not on your care
A planned response to uncertainty can help you decide what information to seek next.
Researchers Peter Gollwitzer and Paschal Sheeran’s 2006 review examined 94 tests of “if-then” plans and found a positive average effect on goal attainment. The review covers varied goals, not this specific spending problem. An if-then plan may help someone carry out a chosen action; it cannot guarantee a good financial outcome. [7]
Choose one uncertainty and make a plan with an action you control:
- If a family expense comes up, then I will check the bill calendar before promising an amount.
- If I do not know the cost, then I will ask for an estimate.
- If there is not enough money, then I will discuss alternatives rather than silently covering the gap.
Maya’s plan is: “If Mom needs help with a pharmacy cost, I’ll ask the amount and check our plan before offering money.” She can still offer a ride. A ride and an open-ended financial promise are different commitments.
Script: “Let me check what I can contribute, and I’ll get back to you tomorrow.”
Two-minute starter: Finish the sentence: “If I don’t know the cost, then I will ______.”
Obstacle and fix: If you feel pressured to answer immediately, practice asking for a specific amount of time: “Can I confirm this evening?”
Track it: Count whether you followed your planned next action, not whether the other person liked the answer.
When it may not work: An emergency may leave little time to plan. A plan cannot guarantee that others will accept a limit or that an expense will be manageable.
4. Share the actual decisions, where it is safe
A specific conversation can make an invisible decision visible.
The CFPB includes tools for starting money conversations and mapping a household’s money picture. Those tools support organizing a discussion; they do not prove that any particular script will resolve conflict. [5]
Choose a calm time and ask about one decision, not every family problem at once:
- State the facts you know.
- Identify what is still unknown.
- Ask who will find out the missing information.
- Agree when to revisit the decision.
Maya tells her partner: “My shoes are $38, and I’m worried Mom may need help at the pharmacy. Can we look at the bills tonight and decide what we can offer if there’s a cost?”
Her partner offers to check the upcoming household bills while Maya asks her mother whether she expects a payment. They agree to talk again after work tomorrow. No one has to solve the whole year before dinner.
Script: “I don’t need you to tell me it’s fine. I need us to look at the numbers together.”
Two-minute starter: Send a message asking for a ten-minute check-in at a specific time.
Obstacle and fix: If the conversation turns into blame, return to the one decision: “Can we first work out what is due before payday?”
Track it: Write down who agreed to do what, and when you will revisit it.
When it may not work: This assumes the other person can participate safely and in good faith. If someone monitors your money, threatens you, or retaliates when you ask questions, a joint conversation may increase risk. Seek private support instead.
5. Build a personal line item only if the money exists
A personal line item can make your needs visible in the plan, but it is not a requirement and it does not have to be the same every month.
The CFPB’s spending and cash-flow tools can help you see income, expenses, and timing. The suggestion to include a personal category is a practical application of those tools, not a tested treatment for guilt. [5]
After listing essential obligations and known care costs, decide whether any amount is genuinely available. If so, write it down alongside the family categories—not as a secret prize that disappears whenever you feel uncomfortable.
Maya and her partner may find that $38 fits this pay period, that only part of it fits, or that the shoes must wait. If the shoes must wait, they can write down a date to check again and explore a repair or lower-cost replacement. A delayed purchase is a financial decision; it need not become a judgment about her value.
Script: “Let’s include my replacement shoes in the plan and see what the numbers allow.”
Two-minute starter: Add one line labeled “my needs” to the bill list. Leave the amount blank if you do not know it.
Obstacle and fix: If the category keeps being emptied for surprises, review whether the household is underestimating recurring costs. Do not assume the problem is a lack of discipline.
Track it: At the next check-in, note whether the category remained realistic and whether any purchase caused a bill to go unpaid.
When it may not work: If essentials are already short, setting aside money you do not have can add pressure. A zero-dollar month is information, not a moral failure.
6. Ask for support beyond the household
When the numbers do not work, the next step may be a resource or professional—not a better attitude.
The CFPB’s toolkit includes a bill-prioritization tool for times when cash is short. A qualified financial counselor can help you review options for your situation; a licensed mental health professional can help if worry or guilt is disrupting daily life. Neither can promise to remove the underlying financial strain. [5]
Maya could start by asking her mother whether the pharmacy has an estimate and whether someone else can share a ride or another task. If bills remain short, she can use the CFPB tool to prepare for a conversation with a financial counselor.
Script: “I’m trying to cover the essentials and help my family. Can you help me understand my options?”
Two-minute starter: Write down the one problem you need help with: “I don’t know which bill to address first,” or “I need help finding care support.”
Obstacle and fix: If explaining everything feels exhausting, bring the short bill list and begin with that one sentence.
Track it: Note the next contact or question—not whether the entire situation is fixed.
When it may not work: Eligibility rules, waitlists, costs, and local availability can limit support. Ask about fees and qualifications before sharing sensitive information or agreeing to a service.
When the budget is short, compassion is not a substitute for resources.
What if there is no room for a personal purchase?
If there is no room after essential costs, you can postpone a purchase without treating your need as unimportant.
Start with a short checklist:
- List bills and essentials due before the next income arrives.
- Separate confirmed care expenses from possible ones.
- Identify one person or service to ask about the shortfall.
- Set a date to revisit your own need, especially if it affects health or work.
If the item is urgent, consider whether it can be repaired, obtained at lower cost, borrowed, or addressed through a local assistance program. These options may not be available or suitable. A pair of shoes that does not fit, for example, is not a useful bargain.
Not every act of care costs money. A rest, a call with someone supportive, or asking another person to handle a task may be available—but none replaces necessary goods or adequate income.
If you are supporting a relative who lives elsewhere, caring for a friend rather than a parent, or do not have children, the same decision framework may still be useful. Your responsibilities do not need a particular family label to count.
If money or spending is controlled by someone who threatens or intimidates you: Your safety comes before a budget conversation. The National Domestic Violence Hotline can help with safety planning: call 800-799-7233 or text START to 88788. If your device may be monitored, consider using a safer device; the Hotline warns that internet use cannot be completely erased. [8]
What happened to Maya’s shoes?
Maya and her partner check the household bills. Maya asks her mother what she expects to pay at the pharmacy. Once they have those answers, they can decide whether the $38 fits this pay period.
The scene stops there because the honest ending depends on information they have not yet gathered. Maya’s progress is not that she has bought something, or that guilt has vanished. It is that she has stopped letting an undefined future expense make the decision by itself.
You can care deeply about your family and still put your own needs on the page. The next step is not to win an argument with your feelings. It is to give the decision enough facts—and yourself enough fairness—to make it.
FAQ
Is it selfish to spend money on myself when my family needs help?
Not inherently. The relevant questions are what your family needs, what the purchase costs, and what your household can afford. Your needs count too. Sometimes the responsible choice is to buy; sometimes it is to wait or seek another option.
Why do I feel guilty even when I can afford something?
You may be worried about future expenses or feel responsible for putting others first. Those are possibilities, not a diagnosis. If the numbers support the purchase but guilt remains, try naming the concern without calling yourself selfish. A therapist can help if the feeling is persistent or disruptive.
What if my family’s needs never seem to end?
Separate known costs from possible future costs, then decide what you can actually offer. Where safe, share that decision with others who are involved. You do not have to resolve every future need before recognizing your own.
Should I create a personal-spending budget?
It can be useful if money remains after essential obligations and realistic care costs. Keep the amount flexible and revisit it as circumstances change. If there is no money left, do not force a category that makes essentials harder to cover.
Where can I get help if the stress becomes overwhelming?
A licensed mental health professional or qualified financial counselor may help, depending on the problem. In the U.S., if you are in emotional crisis, call or text 988 for free, confidential support; you do not have to be suicidal to reach out. [9]
Sources
- Ally/YouGov, 2026: The Cost of Life Today; also reported by TIME.
- AARP, 2026: Caregiving Out-of-Pocket Costs Study. Sample size also reported by NPR.
- NPR, 2026: What’s gone up even faster than gas or rent? The cost of caregiving.
- USA TODAY, 2026: Sandwich generation costs led her to bankruptcy.
- Consumer Financial Protection Bureau, toolkit updated 2020: Your Money, Your Goals.
- Wakelin, Perman and Simonds, 2021 online; 2022 journal issue: Self-compassion interventions and self-criticism: systematic review and meta-analysis.
- Gollwitzer and Sheeran, 2006: Implementation intentions and goal achievement: a meta-analysis.
- National Domestic Violence Hotline: Get help and safety information.
- 988 Suicide & Crisis Lifeline: Get Help.
Disclosure: Maya and her scene are fictional composites, not a real person’s account. Survey findings are self-reported; the behavioral studies concern related outcomes rather than this specific scenario. This article is educational and is not medical, legal, or individualized financial advice.